Starvard University · Taxes 101
Pay what you owe, not a dollar more. Taxes are a system with rules, and the rules reward people who understand them.
The whole course in brief
The twelve lessons
Lesson 1
The US federal income tax is progressive, which means it taxes your income in slices called brackets. The first slice is taxed at 10 percent, the next at 12 percent, then 22, and so on. Crucially, only the dollars inside each bracket get that bracket's rate. Earning enough to enter the 22 percent bracket does not tax all your income at 22 percent, only the dollars above the line.
This kills the most common tax myth: that a raise can leave you poorer by pushing you into a higher bracket. It cannot. The higher rate applies only to the new dollars. Your marginal rate, the tax on your next dollar earned, is what matters for decisions. Your effective rate, total tax divided by total income, is always lower.
Your taxable income is not your salary. It is your salary minus adjustments (like retirement contributions and student loan interest), minus either the standard deduction or your itemized deductions. Everything in this course is about legally shrinking that taxable income number.
Lesson 2
Filing is mostly an organization project. The core documents: W-2s from every employer, 1099s for freelance and contract income, 1099-INT and 1099-DIV for bank interest and dividends, 1099-R for retirement distributions, and records of any estimated tax payments you made. Employers must send these by January 31, so start your folder in February.
Then the deduction and credit paperwork: mortgage interest statements (Form 1098), property tax records, charitable donation receipts, student loan interest statements, HSA contribution records, and childcare expense receipts. Create one folder, physical or digital, labeled with the tax year, and drop everything in as it arrives.
If you moved, changed jobs, got married, had a kid, or started freelancing, note it. Life changes are tax changes, and they are where most missed deductions hide. A new baby, for instance, can mean thousands in credits you would never find by just copying last year's return.
Lesson 3
Every taxpayer gets to subtract either the standard deduction, a flat amount set by law, or their itemized deductions, the sum of specific deductible expenses. You pick whichever is bigger. For most people, especially renters without huge medical bills, the standard deduction wins easily.
Itemized deductions include mortgage interest, state and local taxes (capped at $10,000), charitable donations, and medical expenses above 7.5 percent of your income. Add them up; if the total beats the standard deduction, itemize. Tax software does this math for you automatically.
One strategy worth knowing: bunching. If your itemized deductions hover just under the standard amount, you can bunch two years of charitable giving into one year, itemize that year, and take the standard deduction the next. Donor-advised funds make this easy for charitable givers.
Lesson 4
A deduction reduces the income you are taxed on. A credit reduces your tax bill directly. A $1,000 deduction saves someone in the 22 percent bracket $220. A $1,000 credit saves them $1,000. Credits are worth roughly four to five times more than deductions of the same size, so always hunt credits first.
The big ones for regular people: the Child Tax Credit, the Earned Income Tax Credit for lower earners, education credits (American Opportunity and Lifetime Learning) for tuition, the Saver's Credit for retirement contributions at modest incomes, and energy credits for things like heat pumps, solar, and efficient windows.
Credits have income phaseouts and fine print, which is why tax software earns its keep: answer the interview questions honestly and let it find them. But knowing credits exist means you will not skip the questions or toss the tuition statement that unlocks one.
Lesson 5
The tax code's biggest gift to regular people is tax-advantaged retirement accounts. Traditional 401(k) and IRA contributions are deducted from this year's taxable income, the money grows tax-deferred, and you pay tax on withdrawal in retirement. Roth versions flip it: no deduction now, but withdrawals in retirement are tax-free.
For most young earners, the traditional 401(k) up to the employer match is the first move, because the match is free money and the deduction lowers today's bill. High earners love traditional accounts for the immediate tax cut. Young low earners often prefer Roth, paying low taxes now to get tax-free growth for decades.
The HSA, available with high-deductible health plans, is the stealth superstar: contributions are deductible, growth is tax-free, and withdrawals for medical expenses are tax-free. Triple tax-advantaged. If you have access to one and can afford to contribute, it is the best account in the tax code.
Lesson 6
Side income is taxed, and nobody withholds it for you. Freelancers owe both income tax and self-employment tax (Social Security and Medicare, 15.3 percent on most of it). The rule of thumb: set aside 25 to 30 percent of every freelance payment in a separate savings account the day it arrives. Future you will be grateful.
The IRS expects quarterly estimated payments if you will owe more than $1,000 beyond withholding. The deadlines are roughly mid-April, mid-June, mid-September, and mid-January. Miss them and penalties accrue, though the safe harbor rule protects you: pay at least 100 percent of last year's tax (110 percent for higher earners) and you avoid penalties even if you underpay this year.
The upside of freelancing is deductions employees never get: the home office, business mileage, equipment, software, health insurance premiums if self-employed, and half the self-employment tax itself. Track every business expense from day one; a simple spreadsheet or app beats a shoebox of receipts in April.
Lesson 7
Your employer withholds taxes from each paycheck based on the W-4 you filled out. A big refund means you overpaid all year and gave the government an interest-free loan. Owing a big bill means you underpaid. The sweet spot is close to zero: a tiny refund or a tiny amount owed.
Life changes demand a new W-4: marriage, divorce, a new baby, a second job, or big freelance income. The IRS withholding estimator, free online, takes ten minutes and tells you exactly what to put on the form. Submit the updated W-4 to your employer's payroll and the fix starts with the next paycheck.
Owing a little at filing time is not a problem. Penalties generally apply only if you owe more than $1,000 and paid less than 90 percent of this year's tax or 100 percent of last year's. A $200 balance due in April just means your withholding was nearly perfect.
Lesson 8
Most people have three good options. IRS Free File and the major tax software products handle W-2 income, investments, freelance income, and common deductions with an interview that asks plain-English questions. This covers the vast majority of returns accurately and cheaply.
A CPA or enrolled agent earns their fee when life gets complex: rental properties, business income, stock options, multi-state situations, or an audit. Expect a few hundred dollars for a straightforward complex return. Ask what they charge upfront and whether they will represent you if the IRS asks questions.
File by April 15, or file Form 4868 for an automatic six-month extension. Note the trap: an extension extends the paperwork deadline, not the payment deadline. If you will owe, pay your best estimate by April 15 to stop interest and penalties from growing.
Lesson 9
Missing the filing deadline without an extension triggers failure-to-file penalties that grow monthly and are far worse than failure-to-pay. Even if you cannot pay the bill, file the return. The IRS offers payment plans to almost everyone who asks; the penalty for silence is always worse than the penalty for honesty.
Other classics: forgetting a 1099 (the IRS gets a copy too, and their computer will notice), entering the wrong bank account for direct deposit, misspelling names so they do not match Social Security records, and forgetting to sign. Tax software catches most of these, which is another argument for using it.
The sneakiest mistake is ignoring estimated payments on side income, then getting hit with a four-figure bill plus penalties in April. If this is your first freelance year, the quarterly system feels annoying until the first April you do not panic. Set the calendar reminders now.
Lesson 10
Open it the day it arrives. Most IRS letters are not audits; they are math corrections, missing forms, or identity verification requests. The letter explains exactly what the IRS thinks and what it wants from you, usually with a deadline of 30 to 60 days. Read it twice before reacting.
Common notices: CP12 (math correction, usually in your favor or neutral), CP2000 (income reported to the IRS that was not on your return; often a forgotten 1099), and identity verification letters (prove you are you, then your refund releases). Each has a specific response path printed right on it.
Real audits are rare for regular earners and usually happen by mail, focused on one or two items. Respond honestly, provide exactly what is asked, and consider a CPA or enrolled agent if the amounts are large. And never ignore a letter; deadlines are real and silence is interpreted against you.
Lesson 11
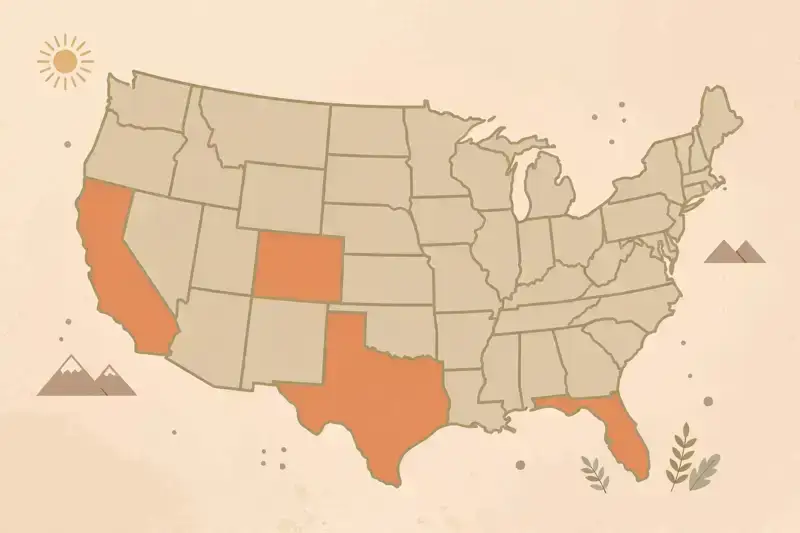
Nine states have no income tax at all, and the rest range from flat low rates to California-style progressivity. Your state return usually starts from your federal adjusted gross income and applies its own rules. State software is typically bundled with federal filing.
Remote workers should know that working in multiple states can create filing obligations in each, and some states aggressively pursue former residents. Keep records of where you lived and worked. Moving mid-year usually means part-year returns in two states.
The state and local tax deduction on your federal return is capped at $10,000, which matters most in high-tax states. Beyond that, the main state-level moves are the same as federal: contribute to retirement accounts, which most states also favor, and know your state's credits for things like rent, childcare, and education.
Lesson 12
January: W-2s and 1099s arrive; open this year's tax folder. April 15: file or extend, pay what you owe, and make first-quarter estimated payments. Mid-June and mid-September: estimated payments two and three. December: the real tax-planning month, harvest investment losses, max retirement contributions, and make charitable gifts.
Mid-January: final estimated payment for the prior year. Throughout the year: save every tax document in the folder the day it arrives, track freelance income quarterly, and adjust withholding after any life change instead of waiting for April.
The December moves deserve emphasis because they are the only tax planning with a deadline. Retirement contributions, charitable donations, and loss harvesting must happen by December 31 to count for that year. Put a calendar reminder for the first week of December: "tax moves." Future you keeps the savings.
Graduation
You understand brackets, you know credits beat deductions, you have a folder system, and you know when to call a pro. Taxes will never be fun, but they are no longer mysterious, and mysterious is where overpaying lives. Pay what you owe, not a dollar more.
Keep learning
This course is part of Starvard University, striving for greatness.